Agentic AI in banking: 5 ways it improves customer experience
Last Updated
November 10, 2026
Harsh Rathour
Read Time
Summary
Agentic AI in banking is AI that understands a customer’s context, decides the next step, and completes tasks across banking systems within set controls. It improves customer experience through personalized guidance, proactive alerts, 24/7 multilingual service, natural voice support, and faster handling of fraud disputes and complaints. People keep final decisions on high-risk cases.
What’s on this page
Agentic AI in banking is AI that reads customer context, decides on the next step, and completes the task across banking systems within set controls. It improves customer experience in five ways: personalized guidance, proactive service, always-on multilingual support, natural voice service, and faster handling of fraud disputes and complaints.
Banks already hold years of data on every customer: each payment, each inquiry, each financial decision. Yet most customers still feel their bank does not know them. Service waits to be asked and forgets what happened last time. Customers feel it in hold queues, repeated questions, and generic offers. Some leave without a word.
That quiet churn is expensive. Bain & Company research found that a 5% increase in customer retention can raise profits by 25% to 95% across industries.
Agentic AI closes the gap between what a bank knows and how it serves. This post explains how, where it helps most, and what four banks achieved with it.
Key takeaways
- Agentic AI acts on a customer's context. A chatbot answers a question and stops.
- The biggest experience gains come from high-stakes moments: fraud, credit, and complaints.
- Proactive service lets a bank fix a problem before the customer calls.
- Governance decides whether a bank can run agentic AI at scale. Build it in from day one.
- Four banks in this post show measured results in containment, volume, and processing time.
Learn more: Kore.ai AI for Banking
What is agentic AI in banking, and how is it different from a chatbot?
Agentic AI in banking is AI that perceives a customer's context, reasons across bank data, and takes action in core systems within governance controls. A traditional banking chatbot answers a question inside a narrow scope and hands off when the task needs action. Agentic AI keeps context across sessions and channels, and completes multi-step tasks such as a payment, a dispute, or an account update.
Why did traditional banking AI fail to improve customer experience?
Traditional banking AI failed because it could answer questions but could not act on them. Chatbots had no memory across sessions, no view of earlier interactions, and no access to core banking systems. Every conversation started from zero.
When a customer had a real problem, such as a disputed charge, the chatbot reached its limit. It transferred the customer to a human agent who had no context either. Banks cut inbound call volume, but customer satisfaction did not rise with it.
Agentic AI in banking closes that gap. It keeps context, connects CRM, core banking, fraud, and compliance data, and acts within guardrails.
How does agentic AI personalize banking customer experience?
Agentic AI personalizes banking by reading behavioral signals in real time and using them in every interaction. Signals include spending patterns, product usage, account activity, and life-event indicators. When a customer's savings rise for three months, the AI agent can suggest a way to put that money to work. This differs from personalized marketing, which targets a demographic segment with a product offer.
Customers value practical help most:
- Alerts about upcoming payments
- Explanations of their spending patterns
- Product recommendations that fit their finances
- Guidance on saving or budgeting toward a goal
Agentic AI delivers this inside the conversation, so the customer does not need to switch channels.
McKinsey research shows that genuine personalization in banking can lift revenue by 10 to 15% and improve customer satisfaction scores by 20 to 30%. Customers who feel understood do not just stay longer. They spend more, go deeper, and bring others with them.
How does agentic AI deliver proactive customer service in banking?
Agentic AI delivers proactive service by watching account activity and reaching out when the data signals a problem. Examples:
- A direct deposit has not cleared, and rent is due in five days.
- An account is close to its overdraft limit three days before payday.
- A loyal customer's activity starts moving to a competitor.
In each case, the AI agent contacts the customer through their preferred channel with a useful option. That might be a payment deferral, a short-term buffer, or a re-engagement offer. The bank solves the problem before the customer has to ask.
Proactive service matters because customers who never call often leave without warning. In a March 2025 forecast, Gartner named proactive issue identification and resolution as a core potential of agentic AI in customer service. Gartner also predicts that by 2029, agentic AI will autonomously resolve 80% of common customer service issues (Gartner, 2025). The forecast covers customer service across industries, not banking alone.
How does agentic AI provide always-on, multilingual banking service?
Agentic AI provides 24/7 service across voice and digital channels, with the same context and quality at any hour and in any supported language. Traditional service has fixed hours, uneven channels, and language gaps that leave some customers underserved.
The AI agent holds the full thread of each customer relationship across sessions and channels. For multilingual service, it keeps that context in every language, so the customer gets the same answer in Arabic as in English. For banks where many customers prefer a language other than English, this improves service and opens new revenue.
What role does voice AI play in banking customer experience?
Voice AI lets banks resolve complex and urgent issues on the phone, where many customers still prefer to call. For fraud disputes, loan questions, and after-hours problems, customers reach for the phone first.
Real-time voice AI now responds fast enough for natural conversation. Chris Hay, a Distinguished Engineer, notes that voice AI has crossed the 200-millisecond latency threshold for natural conversation [NEEDS SOURCE: link to the statement and confirm his employer]. When the voice agent knows the account history and can complete the task, the call resolves the issue in one contact.
Voice AI also widens access. Customers who find apps hard to use, or who prefer to talk through financial questions, get full service in their language at any hour.
How does agentic AI handle fraud disputes, product guidance, and complaints?
Agentic AI handles these high-stakes moments by gathering the customer's context first and then running the workflow end to end. Fraud disputes, credit questions, and complaints shape whether customers stay or leave.
Fraud reporting and disputes
When a customer reports fraud, the AI agent pulls the relevant account history and transactions. It guides the customer through the report in their preferred channel. It then starts the dispute workflow in line with Visa and Mastercard rules. The customer does not repeat details or wait for a person to pull records.
A U.S. card dispute shows how the work splits between the AI agent and people. Under Regulation E, a bank has up to 45 days to resolve an unrecognized-charge claim.
The AI agent runs the intake, filing, and deadlines. A human analyst makes the final call.
A 2025 MIT Technology Review survey with EY of 250 banking executives found that 56% report high capability in fraud detection, the top agentic AI use case in the survey (MIT Technology Review, 2025).
Product and credit guidance
Agentic AI guides customers to the right product based on what they share. A customer might ask: "I usually keep around $10,000 in my account. Which checking account works best for me?" The AI agent uses that detail to compare options and explain the trade-offs. This works across savings accounts, loans, credit cards, and investment products. Customers get needs-based advice without booking an appointment.
Complaint resolution
Agentic AI resolves complaints with the full picture already assembled. It sees the account history, prior interactions, the issue, and how similar cases were resolved. The customer does not explain the problem twice. A fast, informed response shows the bank was paying attention.
What results are banks seeing from agentic AI in customer experience?
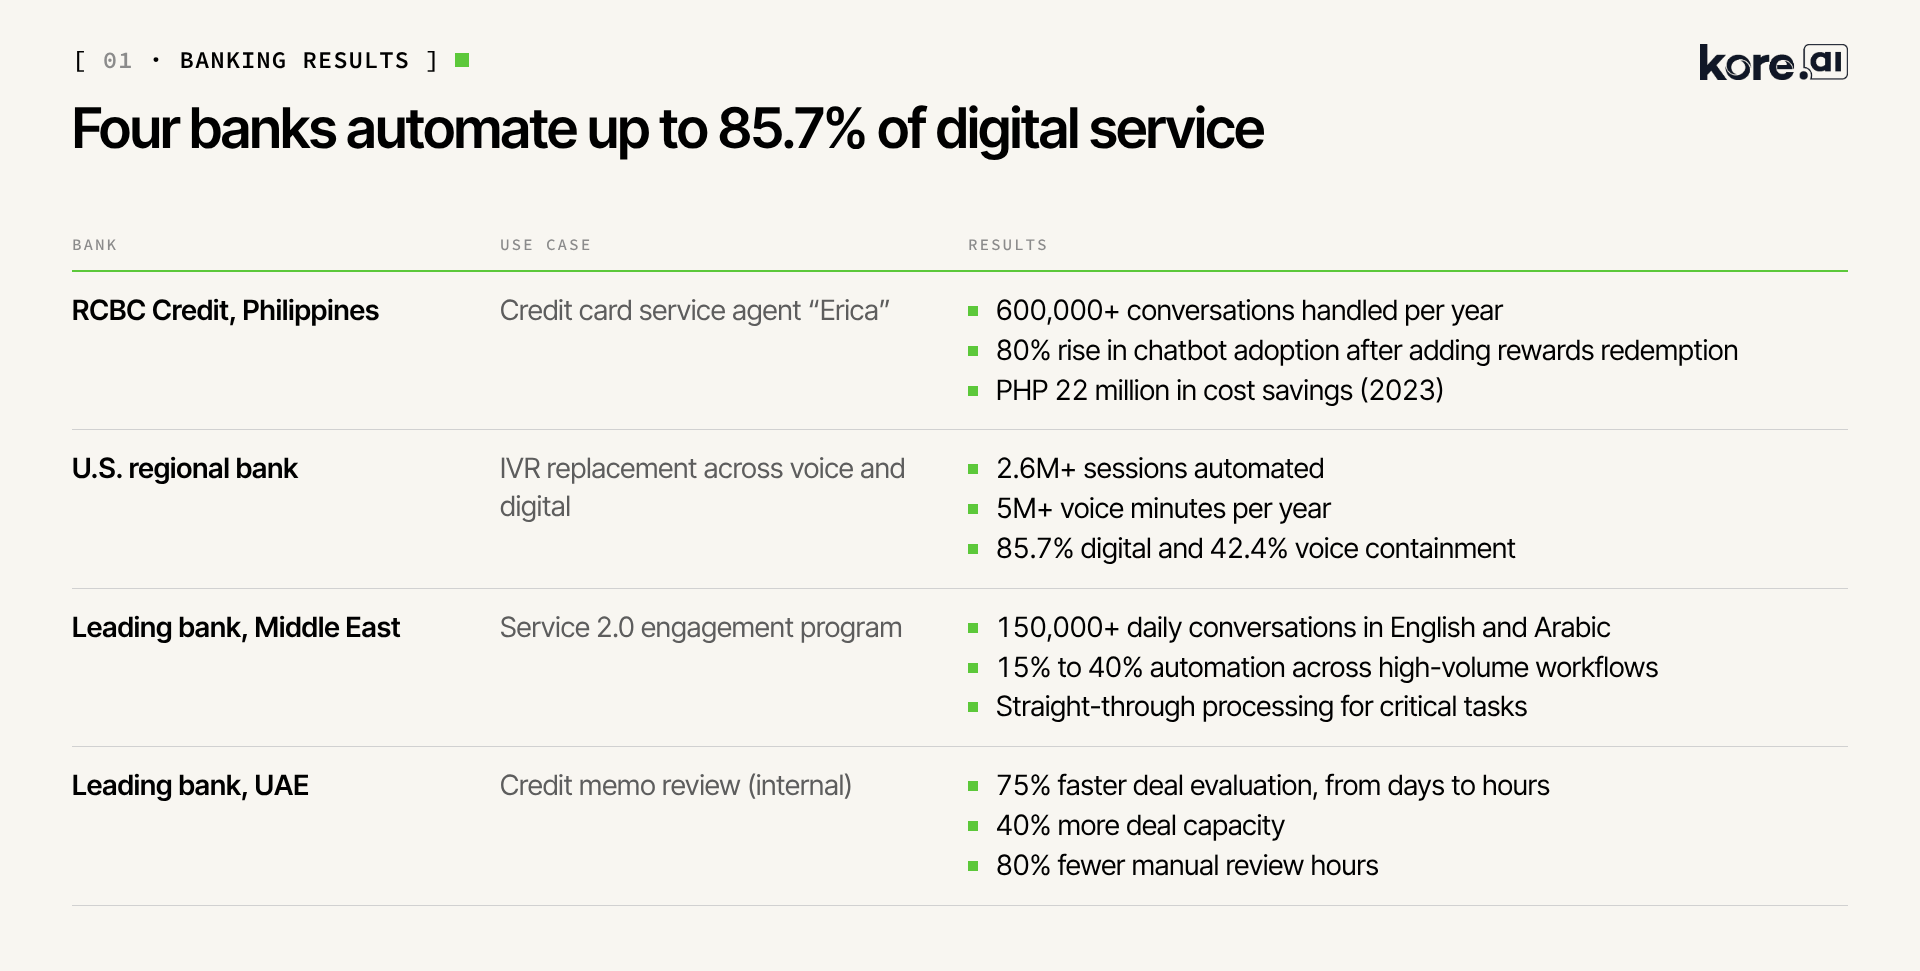
Banks running Kore.ai AI agents report gains in containment, conversation volume, and processing time. Four examples follow.
RCBC Credit: personalization that drives adoption
RCBC Credit serves more than 1.2 million credit cardholders in the Philippines. The bank deployed Erica, a Kore.ai AI agent, with four use cases and expanded to nine. Adoption rose 80% after the bank added rewards redemption inside the conversation. ROI came within the first year. Read the RCBC story.
U.S. regional bank: always-on service at scale
This bank handled more than one million calls a year through a rigid IVR. It replaced the IVR with Kore.ai AI for Banking across voice and digital. Customers now handle balances, payments, card services, and account questions in natural conversation, with handoff to a person when needed. Read the regional bank story.
Middle East bank: multilingual, omnichannel service
This bank wanted consistent service in two languages across every channel. Kore.ai AI agents now run its Service 2.0 program and handle more than 150,000 conversations a day in English and Arabic. Read the Middle East bank story.
UAE bank: faster credit evaluation
Credit teams at this bank spent hours on manual memo review, document parsing, and data validation. InAlpha automated memo summarization and data validation. Deal evaluation dropped from days to hours, and credit officers moved to analysis. Faster evaluation shortens the borrower's wait. Read the UAE bank story.
How widely have banks adopted agentic AI?
As of 2025, 70% of banks were deploying or piloting agentic AI: 16% in production and 52% in active pilots. The figures come from the MIT Technology Review and EY survey of 250 banking executives (MIT Technology Review, 2025).
Adoption does not guarantee returns. That research found 57% of financial services firms use AI agents for customer service, but only 32% report significant returns. Banks that deploy AI only to cut cost gain efficiency. Banks that deploy AI to understand customers build retention.
McKinsey estimates generative AI could add $200 billion to $340 billion in annual value for banking (McKinsey, 2024).
What should banks check before deploying agentic AI in customer service?
Banks should confirm three things before they deploy agentic AI with customers: who is accountable for an autonomous decision, whether the system can explain its actions, and how the bank shows oversight to regulators. Strong deployments start with the highest-friction moments, such as long waits and repeated questions, and measure retention and lifetime value along with cost.
Agentic AI also has limits. Four trade-offs shape every banking deployment:
- Humans keep the judgment calls. The AI agent runs intake, data gathering, filing, and deadlines. People make final decisions on disputes, credit, and exceptions, as in the Reg E example above. This caps full automation, and it keeps every high-risk decision defensible to regulators.
- Regulated steps run deterministically. Agentic AI uses model reasoning to understand intent and context. Steps that must follow a fixed rule, such as identity checks, consent, disclosures, and money movement, run as defined workflows without a model call. Banks must specify these flows up front, which takes design time but makes outcomes repeatable and auditable.
- Integration sets the pace. An AI agent can only act in systems it can reach. Banks with APIs to core banking, cards, and CRM move fastest. Where APIs are missing, RPA can fill the gap, but it adds maintenance. With pre-built banking applications and reachable systems, the first use cases can reach production in weeks.
- Agents need testing before and after launch. Model reasoning can be wrong. Banks should test each agent against simulated customers, edge cases, and adversarial inputs, and block release until it meets set pass criteria. Guardrails should check every input, output, and tool call in production, and tests should re-run on every change.
How does Kore.ai AI for banking support agentic customer experience?
Kore.ai AI for Banking is a set of governed, production-ready AI agents for retail banks, built on the Kore.ai Artemis platform and integrated with core banking systems. Banks deploy pre-built agents instead of building from scratch. The solution covers 240+ retail banking workflows including:
- Account servicing and digital banking support
- Dispute management and complaint resolution
- Card controls and payments
- Fraud detection and risk signals
- Voice and digital customer service
What makes Kore.ai AI for banking different?
- Blended reasoning and deterministic control. AI agents handle intent detection and contextual reasoning. Deterministic workflows run every step that must follow compliance rules.
- Pre-built banking applications. Use cases ship with integration accelerators. The orchestration layer runs multi-step transactions such as payments, disputes, and account updates. Kore.ai pairs these applications with forward-deployed engineers to reach production in weeks.
- Voice and digital parity. Customers get the same context and quality whether they call, chat, or message. System connectors and RPA link legacy core banking, payment, and CRM systems where APIs are not available.
- Governance by design. Observability, explainability, data isolation, model routing, and audit trails are part of the architecture. They answer the three questions above on accountability, explanation, and oversight.
- Multi-model choice. Banks choose models by cost, performance, security, and regulatory need, and change them as the market moves.
Kore.ai AI for Banking is available on Microsoft Azure Marketplace and AWS Marketplace. It integrates with Microsoft Dynamics 365, Agent 365, Amazon Bedrock, and Amazon Connect.
Conclusion: How banks earn trust with agentic AI
Agentic AI in banking turns years of customer data into service that knows each customer. Banks that start with fraud, credit, and complaints see the fastest gains in experience and retention.
Next step: see Kore.ai AI for Banking or Talk to an expert.
FAQ
How does agentic AI in banking improve customer experience?
Agentic AI in banking improves customer experience by acting on each customer's context across channels and systems. It personalizes guidance, reaches out before problems grow, serves customers 24/7 in several languages, and handles fraud disputes and complaints with full context. Banks using Kore.ai AI agents report up to 85.7% digital containment and a 75% cut in credit evaluation time.
What is the difference between agentic AI and a traditional banking chatbot?
A traditional banking chatbot answers questions within a narrow scope and cannot act across systems. Agentic AI keeps context across sessions and channels, runs multi-step workflows in core banking systems, and acts within governance controls. A chatbot tells a customer their balance. An agentic AI system notices the balance is falling and offers a relevant option before the customer asks.
Is agentic AI in banking safe and compliant?
Agentic AI in banking can meet compliance needs when governance is part of the design. Banks should require explainability, full audit trails, human-in-the-loop controls for high-risk steps, data isolation, and role-based access. Every autonomous action should be logged and reviewable. Banks should map these controls to the regulations that apply to them, such as DORA in the EU. More info: Kore.ai Trust Center
How does agentic AI help with fraud in banking?
Agentic AI helps with fraud by speeding up reporting and disputes. When a customer reports fraud, the AI agent gathers the account history and transactions, guides the customer through the report in their preferred channel, and starts the dispute workflow in line with Visa and Mastercard rules. The customer does not repeat details or wait for manual record pulls.
How fast can a bank deploy agentic AI for customer service?
Deployment time for agentic AI in banking depends on three factors: how many use cases go live first, whether core systems expose APIs, and how much compliance review each workflow needs. Most banks start with a few high-volume tasks, such as balance checks, card services, and disputes, then expand. RCBC Credit launched its AI agent with four use cases and grew to nine. Kore.ai pairs pre-built banking applications with forward-deployed engineers to reach production in weeks.
Share
Tags