Agentic AI in financial services and insurance sector
Summary
Agentic AI in financial services and insurance (FSI) enables AI agents to reason, make decisions, and execute multi-step workflows across lending, fraud detection, compliance, KYC, claims, underwriting, and customer service. This article explores multi-agent orchestration, autonomous execution, real-time adaptation, governance, and human oversight, showing how agentic AI can connect fragmented systems and automate complex FSI processes while maintaining compliance and auditability.
What’s on this page
Agentic AI in financial services and insurance (FSI) is the use of AI agents that reason through multi-step problems, make decisions, and execute workflows such as lending, fraud investigation, KYC, claims, and underwriting under guardrails that humans set.
Banks and insurers have spent decades and billions on digital transformation, yet most of that investment automated the edges of the work. Compliance teams still clear hundreds of manual alerts every morning. Loan applications sit in queues for days, and claims adjusters log into system after system to assemble information that should already be in one place. The decisions that drive outcomes, such as risk calls, fraud catches, and compliance rulings, still sit with people. McKinsey's State of AI research finds that 88% of organizations use AI in at least one business function, but only 6% qualify as high performers where AI contributes meaningfully to EBIT.
Agentic AI targets that gap. AI agents connect fragmented systems, resolve standard cases end to end, turn multi-day processes into minutes, and log every decision so regulators can trace it. This guide is for banking and insurance leaders deciding where to deploy agentic AI. It explains what agentic AI is, where it delivers measurable impact, what blocks it from scaling, and how to govern it.
Key takeaways
- Agentic AI executes complete workflows, while traditional automation handles only predictable, rule-based steps.
- The highest-impact FSI use cases are fraud investigation, credit decisioning, KYC, disputes, claims triage, and underwriting. A leading UAE bank using AI agents for credit evaluation cut deal evaluation time by 75%.
- Most institutions still struggle to scale: McKinsey finds no more than 10% of respondents scaling AI agents in any one business function.
- Credit decisioning, fraud detection, and underwriting usually count as high-risk under the EU AI Act, so explainability, audit trails, and human oversight are requirements.
- The safest path is tiered: start with high-volume, lower-risk workflows with humans in the loop, then extend autonomy as performance data earns it.
What is agentic AI in financial services and insurance?
Agentic AI in financial services and insurance is a class of AI systems that perceive context, reason through multi-step problems, make decisions, and take action without constant human intervention. Traditional FSI automation executes pre-programmed rules. Agentic AI works toward an outcome, such as approving creditworthy loans while limiting default risk, and decides which steps reach it.
An analogy helps. Traditional AI behaves like a compliance officer working from a checklist: it waits for input, applies fixed rules, and returns a binary output. Agentic AI behaves like an experienced financial crimes investigator who reads transaction patterns, weighs risk across data sources, checks regulatory constraints, and balances fraud prevention with customer experience in real time.
What capabilities define agentic AI in FSI?
Agentic AI in FSI has four core capabilities:
- Goal-driven reasoning: Agents work backward from an outcome and choose the steps that reach it.
- Multi-agent orchestration: Specialized agents for lending, fraud, claims, and service share context and hand off work.
- Real-time adaptation: Agents adjust to new fraud patterns and regulatory updates without waiting for a model refresh.
- Autonomous execution: Within guardrails, agents run workflows such as loan processing and dispute resolution without approval for every step. Humans set the rules and monitor outcomes.
How is agentic AI different from traditional automation in banking and insurance?
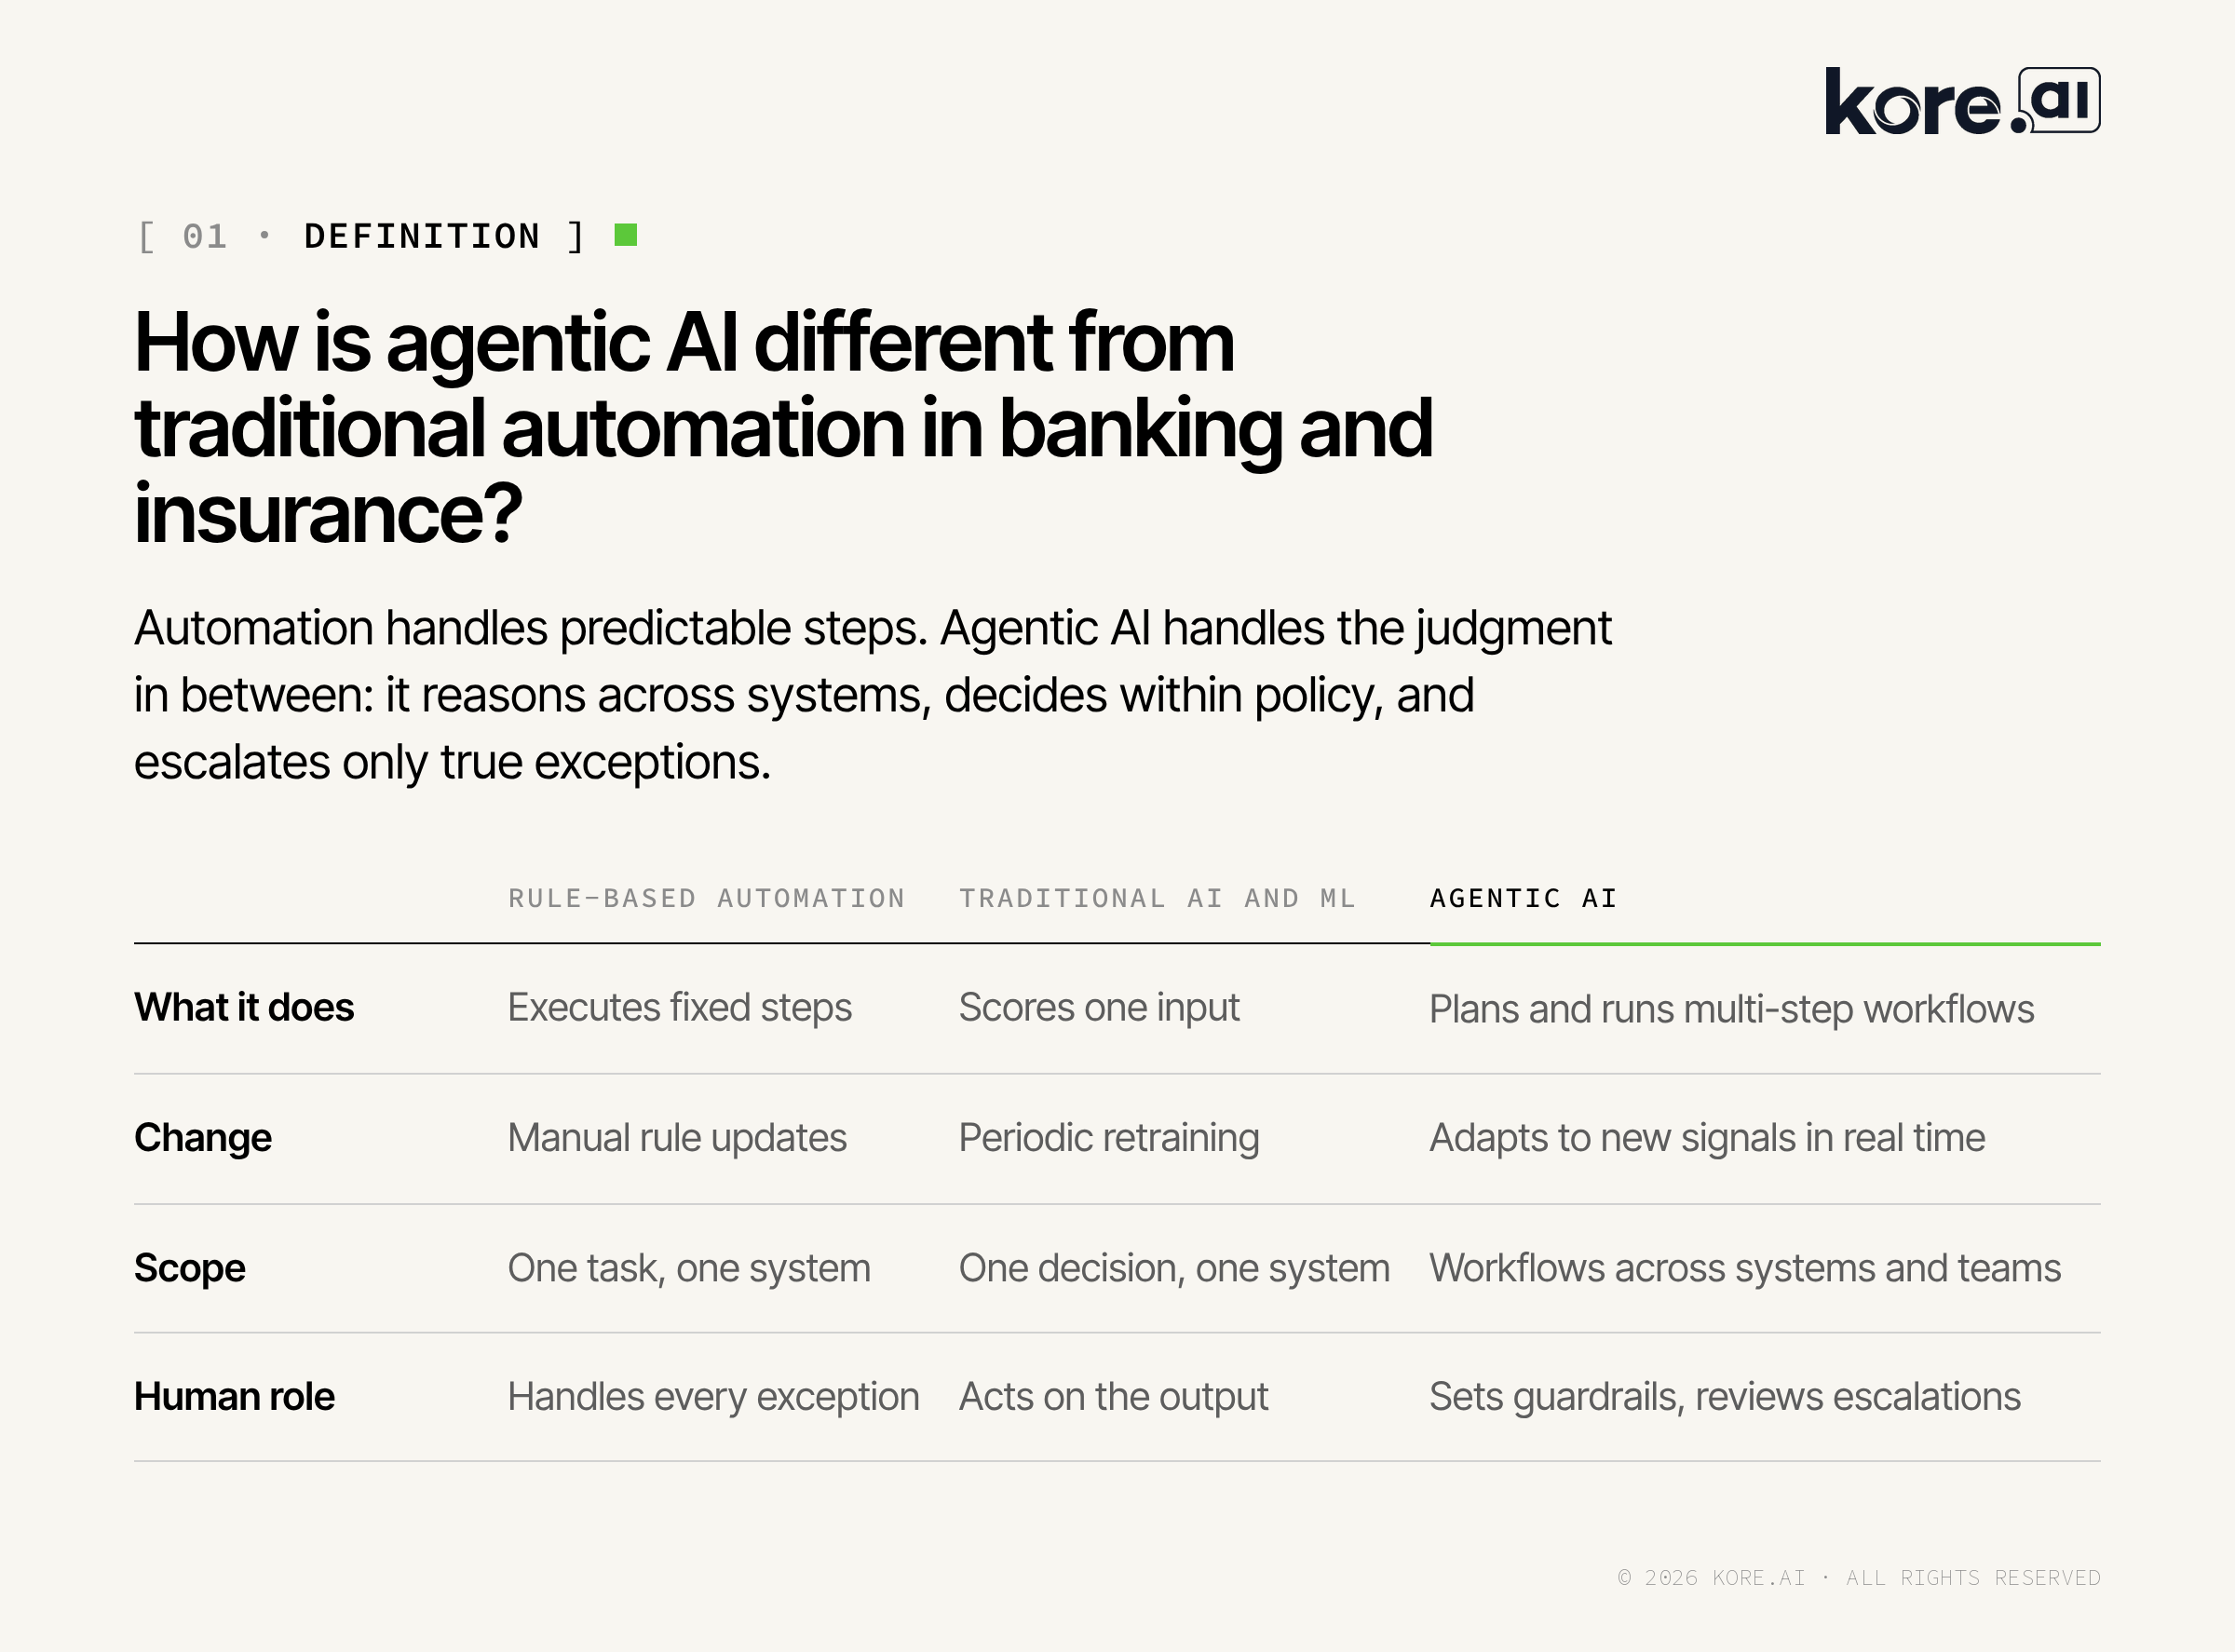
Traditional automation in banking and insurance handles predictable, rule-based tasks and sends everything else to people. Agentic AI handles the judgment-heavy work in between: it reasons across systems, decides within policy, and escalates only true exceptions.
Adoption alone has not fixed this: McKinsey finds only 6% of organizations qualify as AI high performers. Gartner claim by 2030, over 85% of routine transactional finance activities will be managed by AI-driven process automation, fundamentally transforming traditional labor-centric models.
Why do banks and insurers need agentic AI now?
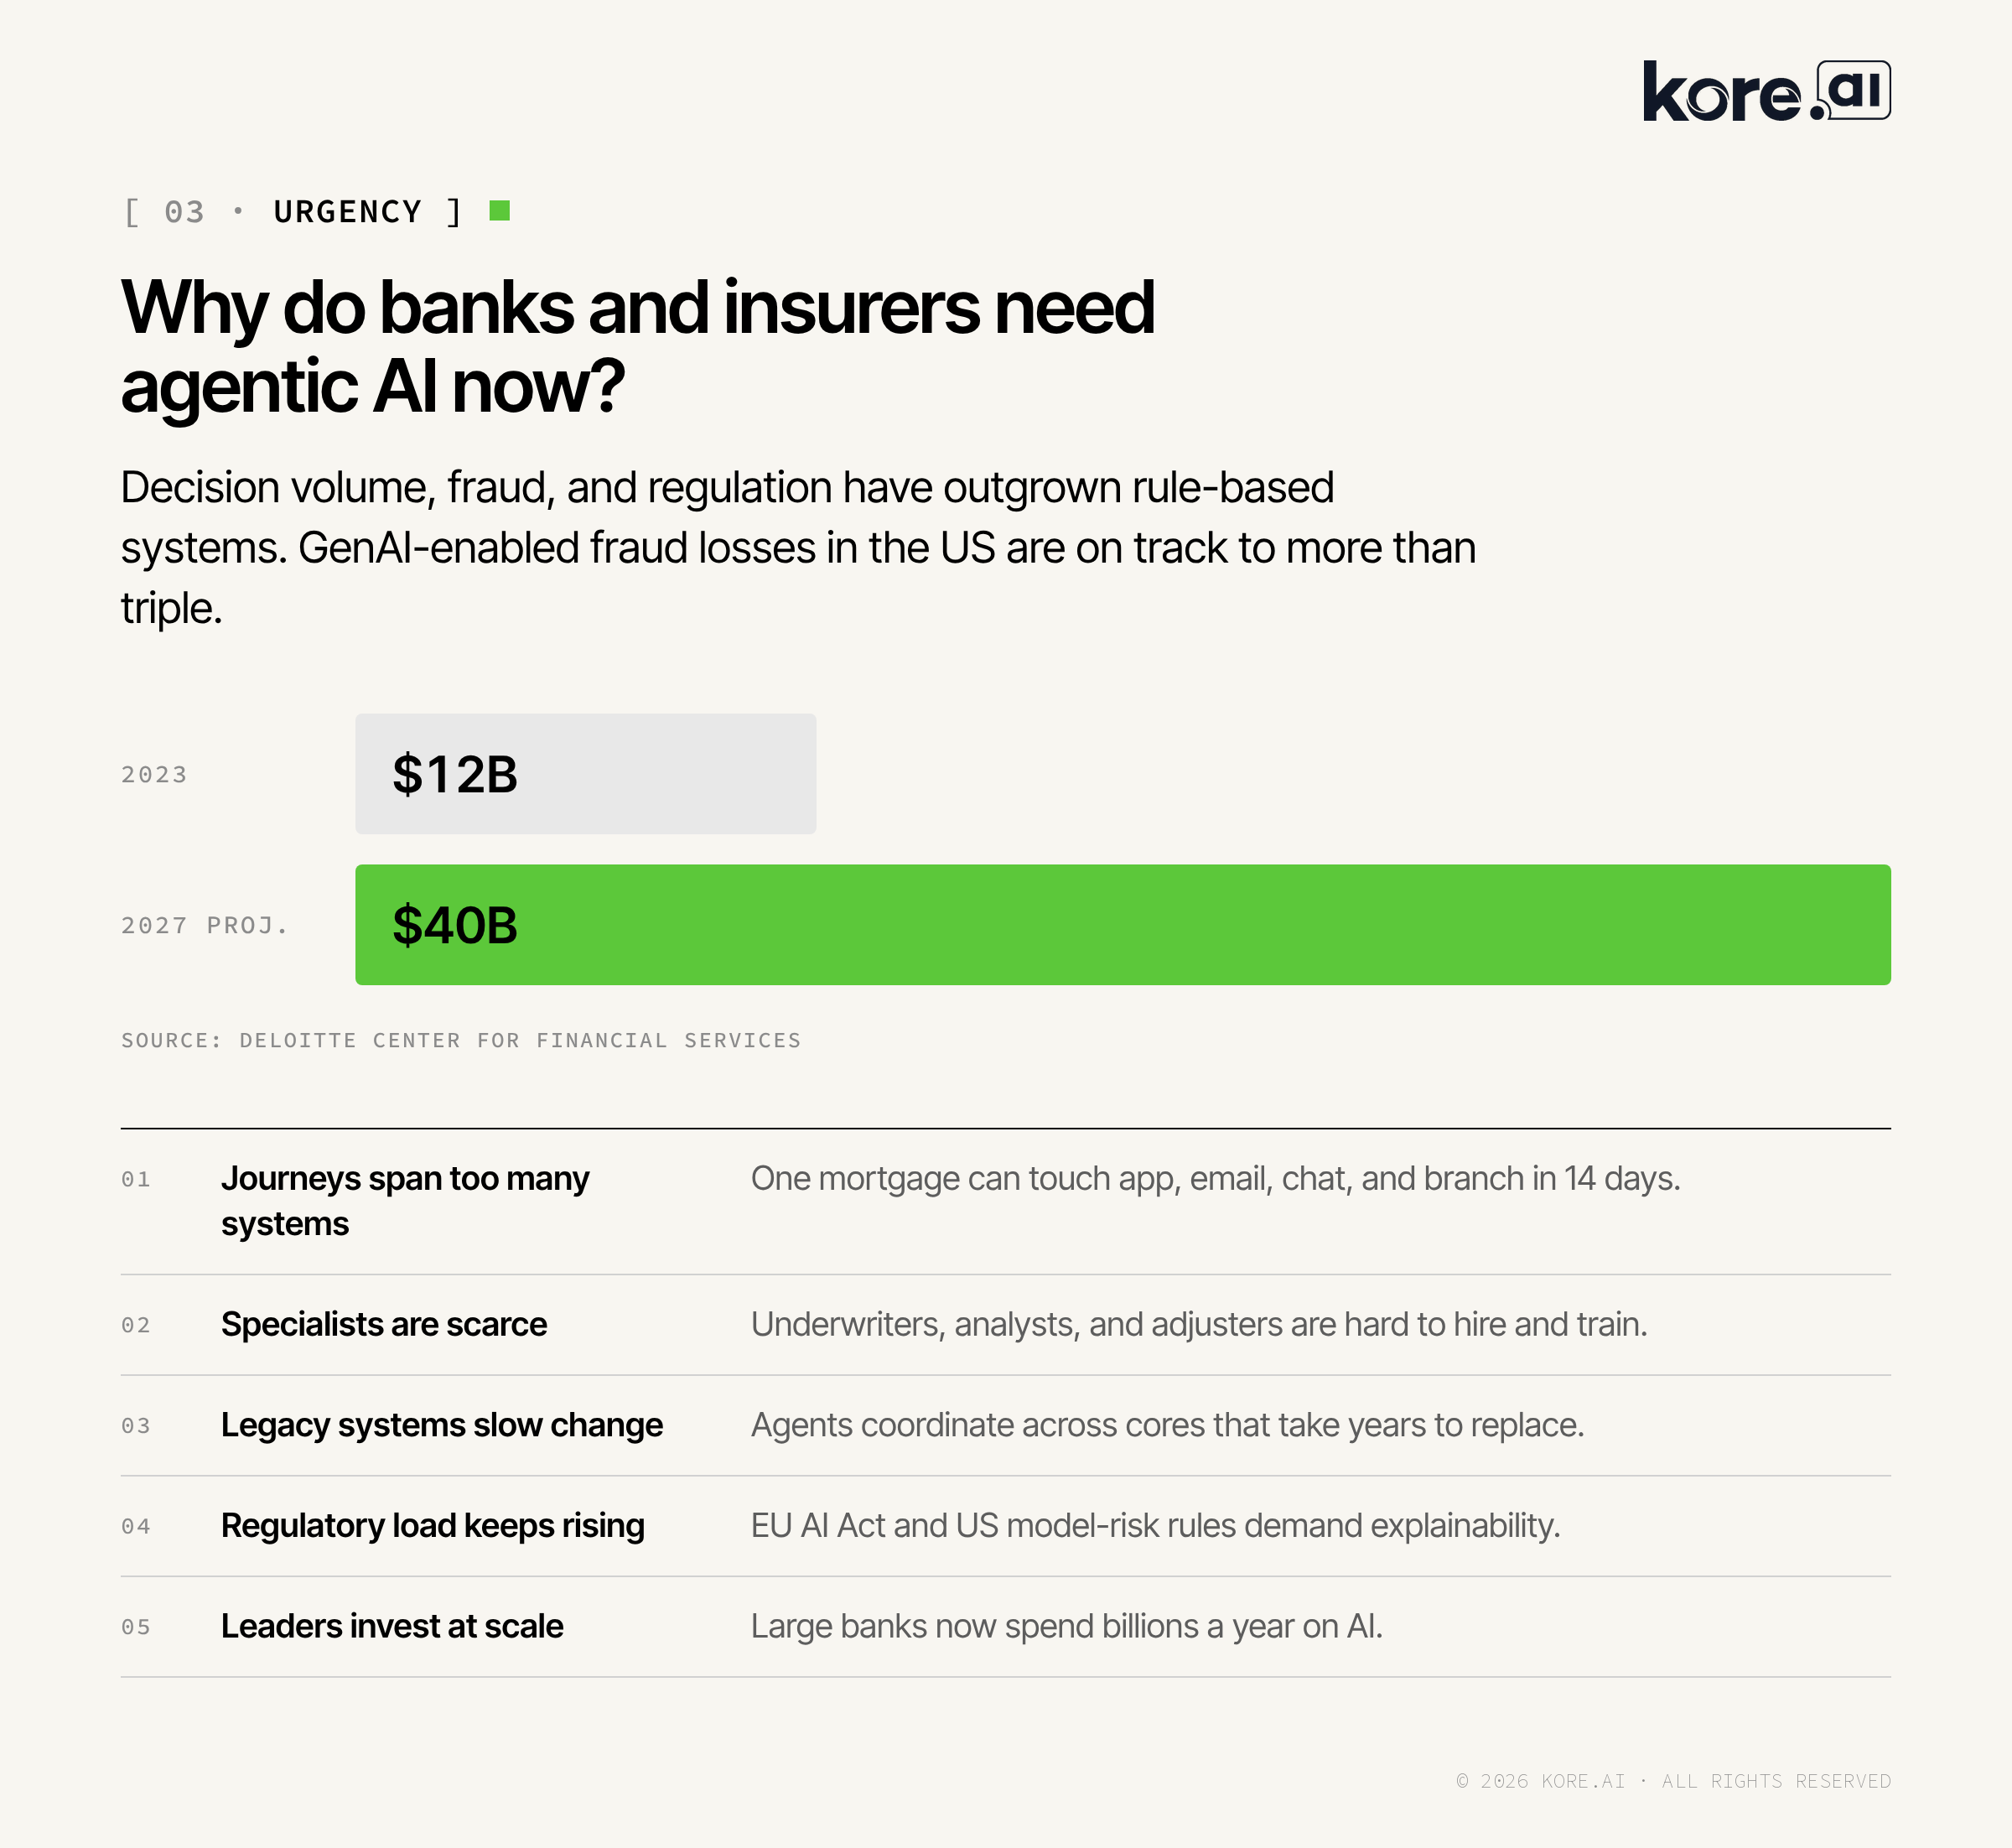
Banks and insurers need agentic AI now because decision volume, fraud sophistication, and regulatory load have outgrown systems designed for rule-based work. The Deloitte Center for Financial Services projects GenAI-enabled fraud losses in the US will grow from $12 billion in 2023 to $40 billion by 2027. Five pressures drive the urgency.
1. Customer journeys span too many systems
A mortgage customer might compare six banks, apply in an app, email documents, and visit a branch, all within 14 days. Each touchpoint creates decisions, such as which documents are missing. Traditional systems make these decisions in isolation. Agentic AI carries context across every interaction.
2. Specialist labor is scarce
Underwriters, compliance analysts, fraud investigators, and claims adjusters are hard to hire and expensive to train. According to Kore.ai's FSI guide [NEEDS SOURCE: link to the guide], compliance teams spend up to 70% of their time on manual data validation. Agentic AI takes on document validation, risk scoring, fraud triage, and claims routing, so specialists focus on exceptions.
3. Legacy systems slow every change
Many banks run 1980s mainframe core systems and rigid loan origination platforms, and many insurers run policy administration systems built before real-time decisions. Full modernization takes years. Agentic AI works across existing systems and adds the coordination they lack.
4. Regulatory pressure keeps rising
The Digital Omnibus moved EU AI Act obligations for stand-alone high-risk systems (Annex III) to December 2, 2027. US regulators are tightening oversight of model risk, third-party governance, and algorithmic bias. Agentic AI built with logging, explainability, bias monitoring, and human-in-the-loop controls lets institutions innovate and stay compliant.
5. Leading institutions are investing at scale
JPMorgan Chase is investing $4 billion in AI in 2025, nearly one-third of its technology budget, according to Tearsheet's AI Reality Check report (Q1 2025). The same report finds Morgan Stanley's AI assistant reached 98% adoption among financial advisor teams and saves 30 minutes per client meeting.
What does the data say about agentic AI adoption in FSI?
The data shows fast adoption and slow scaling. Deloitte predicts that 50% of enterprises using generative AI will deploy agentic AI by 2027, up from 25% in 2025. Citizens Bank's 2026 AI Trends report finds 82% of midsize companies have begun or plan to implement agentic AI in 2026, and 99% of adopters report better operational efficiency and productivity.
- Scaling is the gap: McKinsey finds that in any business function, no more than 10% of respondents report scaling AI agents.
- Data is the top barrier: KPMG finds 48% of organizations cite data governance concerns and 20% say their data is not ready.
- The upside is large: KPMG projects agentic AI could unlock $3 trillion in corporate productivity and a 5.4% annual EBITDA improvement for the average company.
Where does agentic AI deliver measurable impact in banking and insurance?
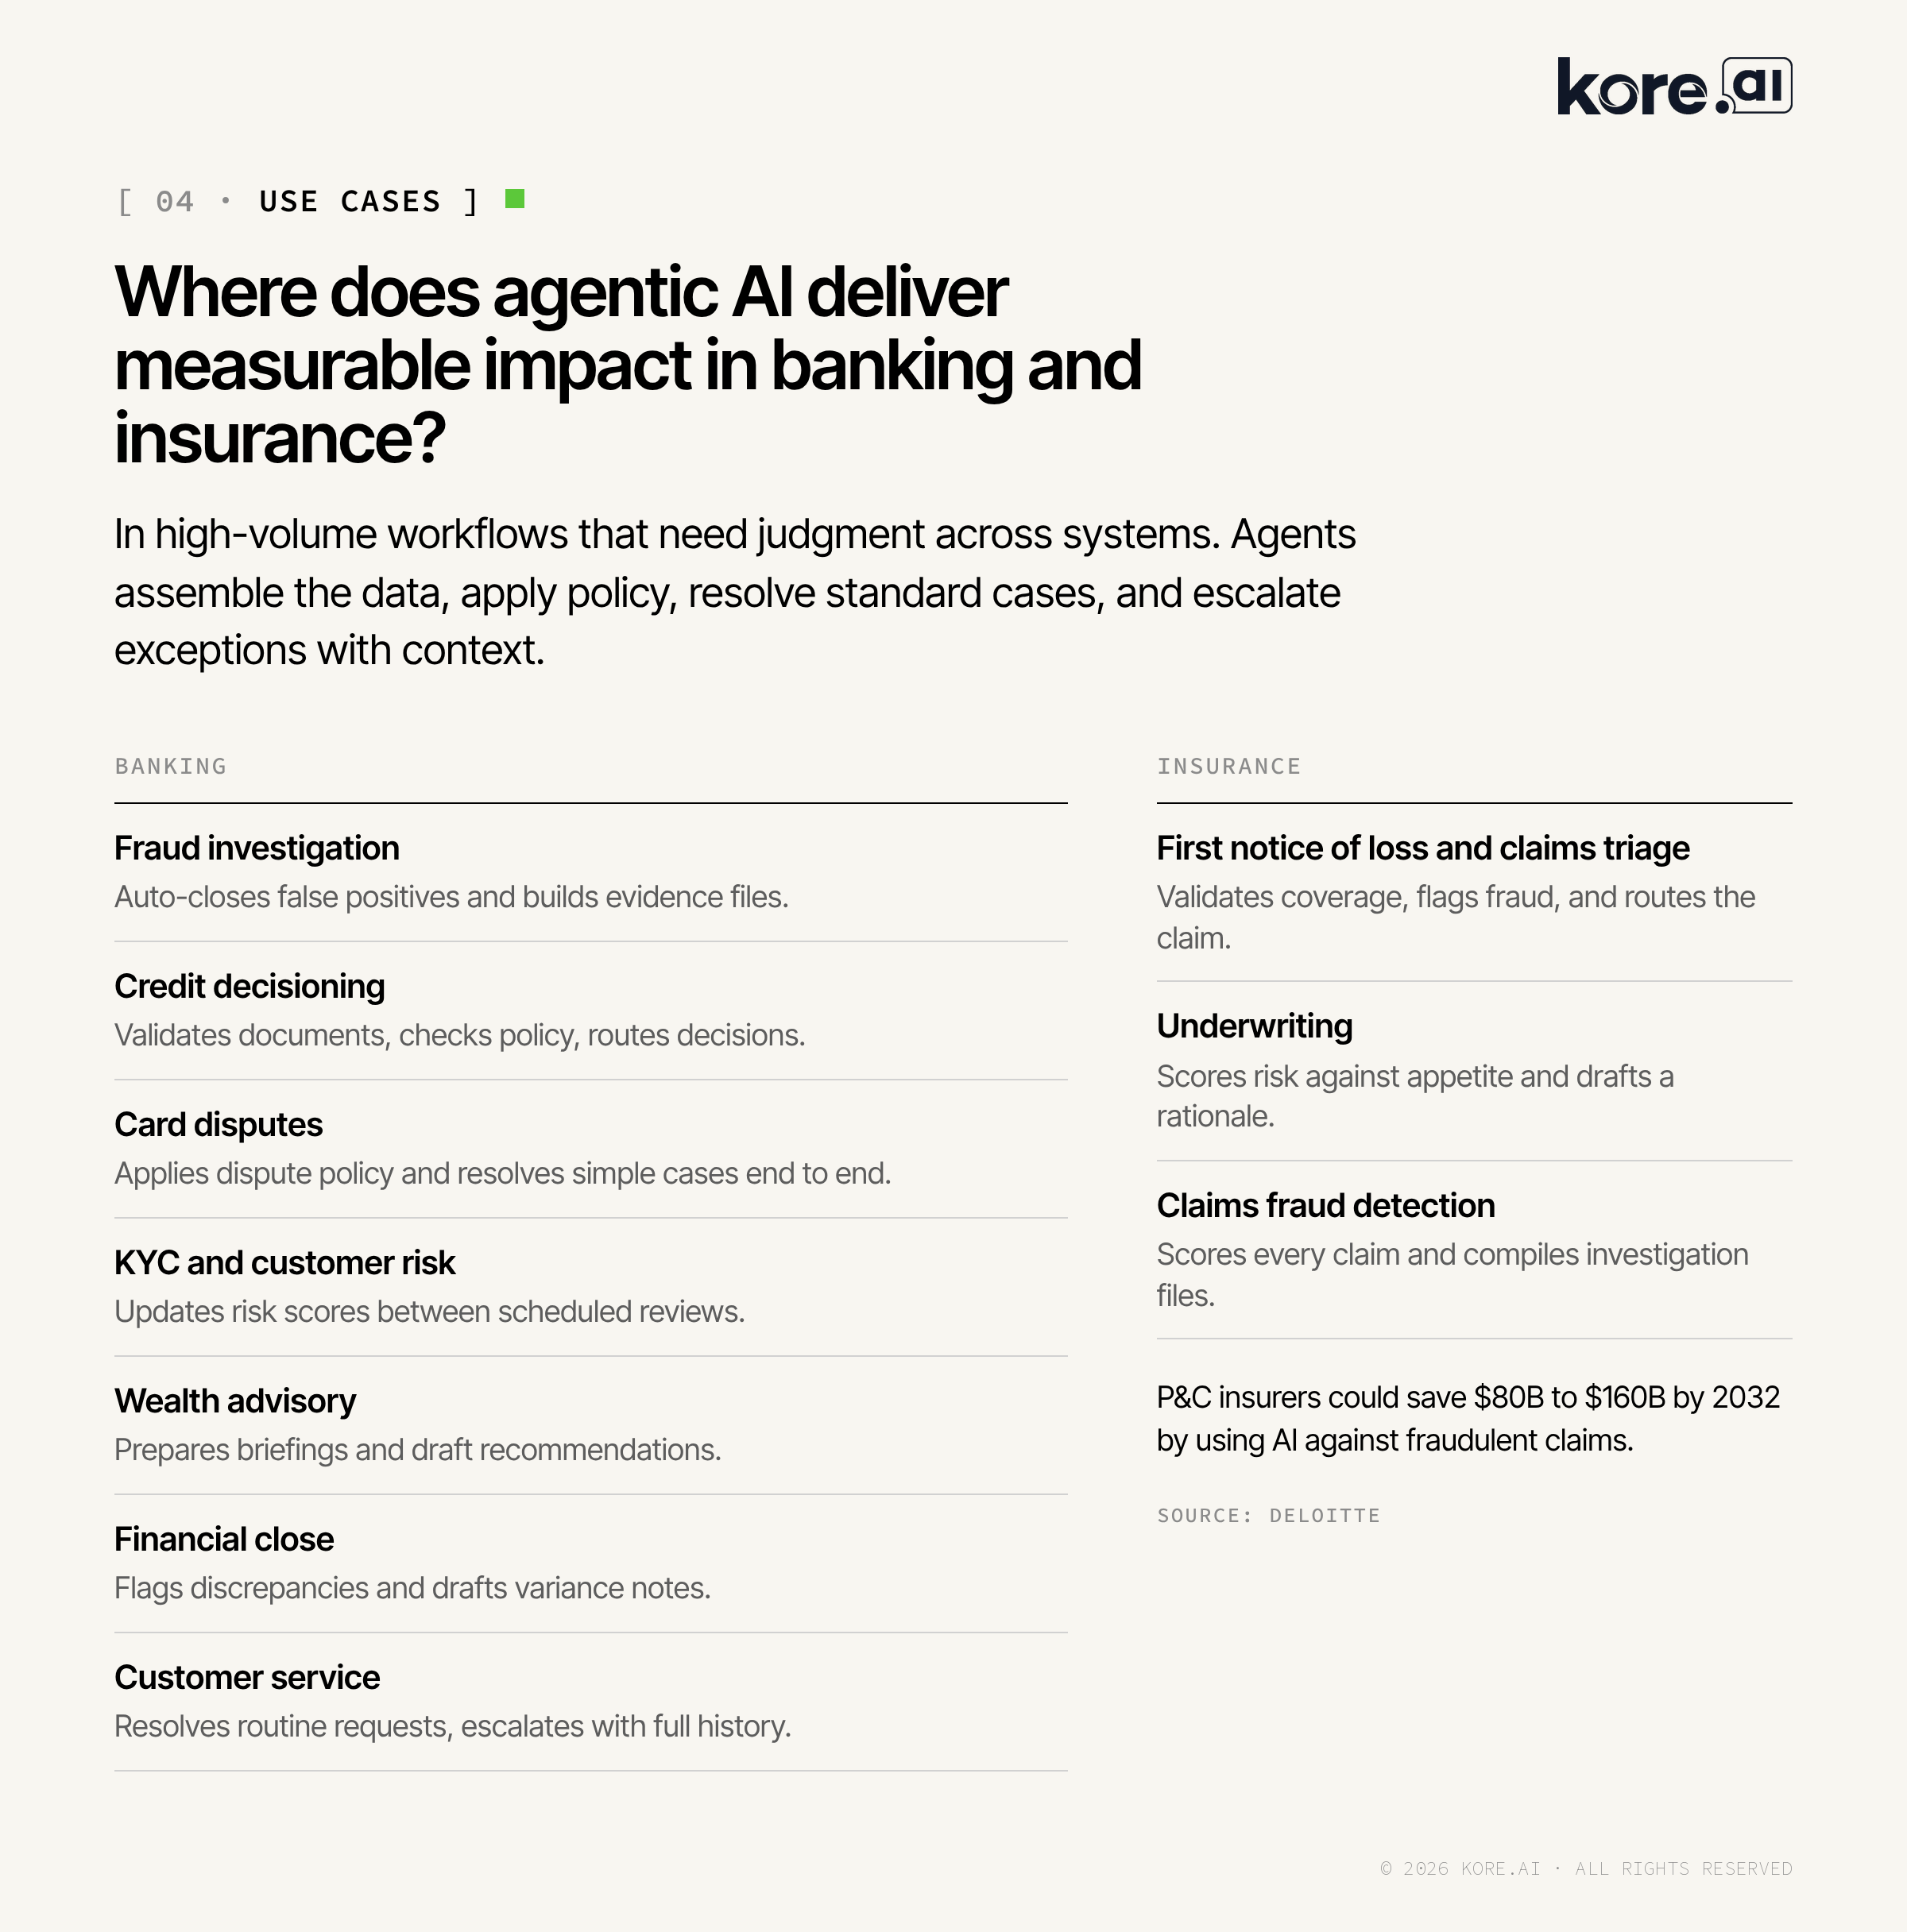
Agentic AI delivers the clearest impact in high-volume FSI workflows that need judgment across several systems. AI agents assemble the data, apply policy, resolve standard cases, and escalate exceptions with context.
What results are banks and insurers seeing with Kore.ai AI agents?
Kore.ai customers in banking, wealth management, and insurance report measurable results in customer service, employee productivity, and credit evaluation. Figures come from published Kore.ai customer stories, as of November 2026.
What business benefits can FSI institutions expect from agentic AI?
FSI institutions can expect lower operating costs, faster service, revenue growth, stronger compliance, and more productive specialist teams from agentic AI. KPMG projects an average 2.3x return on agentic AI investments within 13 months. The size of each benefit depends on data quality and on how much of each workflow agents are allowed to complete.
- Operational efficiency: Agents complete work that rules-based automation hands to people, cutting false positives in fraud and resolution times in service.
- Competitive position: A lender that decides loans in 3 days instead of 10 wins customers who need fast answers. In insurance, McKinsey reports AI leaders delivered 6.1x the total shareholder return of laggards over five years.
- Revenue growth: Agents spot cross-sell signals from life events and transactions, and lower service costs make smaller accounts profitable.
- Regulatory resilience: Agents log every decision with full context, apply encoded rules uniformly, and flag suspicious transactions as they occur instead of in weekly batches.
- Workforce productivity: Specialists move from data gathering to edge cases, disputes, and advisory work. Agentic AI does not end the hiring shortage. It makes existing teams go further.
What are the biggest challenges in implementing agentic AI in FSI?
The biggest challenges in implementing agentic AI in FSI are data infrastructure, legacy systems, explainability, organizational resistance, security, and ROI measurement. These barriers are connected, and governance ties them together. An institution that fixes its data still stalls if accountability and oversight are undefined.
- Data infrastructure: Customer data sits in mainframes, batch files, and systems with different customer IDs and date formats. Agents must reconcile all of it in real time, and cleanup can cost more than the AI budget.
- Legacy systems: COBOL core systems were not built for APIs or the request volumes agents generate. Vendors control many platforms, so API access depends on their roadmaps. Full modernization takes 3 to 5 years.
- Explainability: A loan denial must cite specific factors such as income and debt ratios. Under the EU AI Act, credit decisioning and underwriting can qualify as high-risk, and breaches carry fines of up to €15 million or 3% of global annual turnover. Multi-agent decision paths are harder to validate than single models.
- Organizational resistance: Experienced staff hesitate to hand over decisions they once owned, and accountability for a bad AI call is unclear. Moving to "humans govern AI" needs sustained leadership commitment and cross-functional teams.
- Security: Agents need access to sensitive records, which concentrates risk. Agents can also fail quietly, such as a fraud model that starts missing cases. In FSI, those failures are regulatory events.
- ROI measurement: Teams that define success metrics before go-live prove value faster. Service workflows track resolution time and abandonment. Back-office workflows track cycle time and error rates. Risk workflows track detection rates and audit completeness.
How should banks and insurers govern agentic AI?
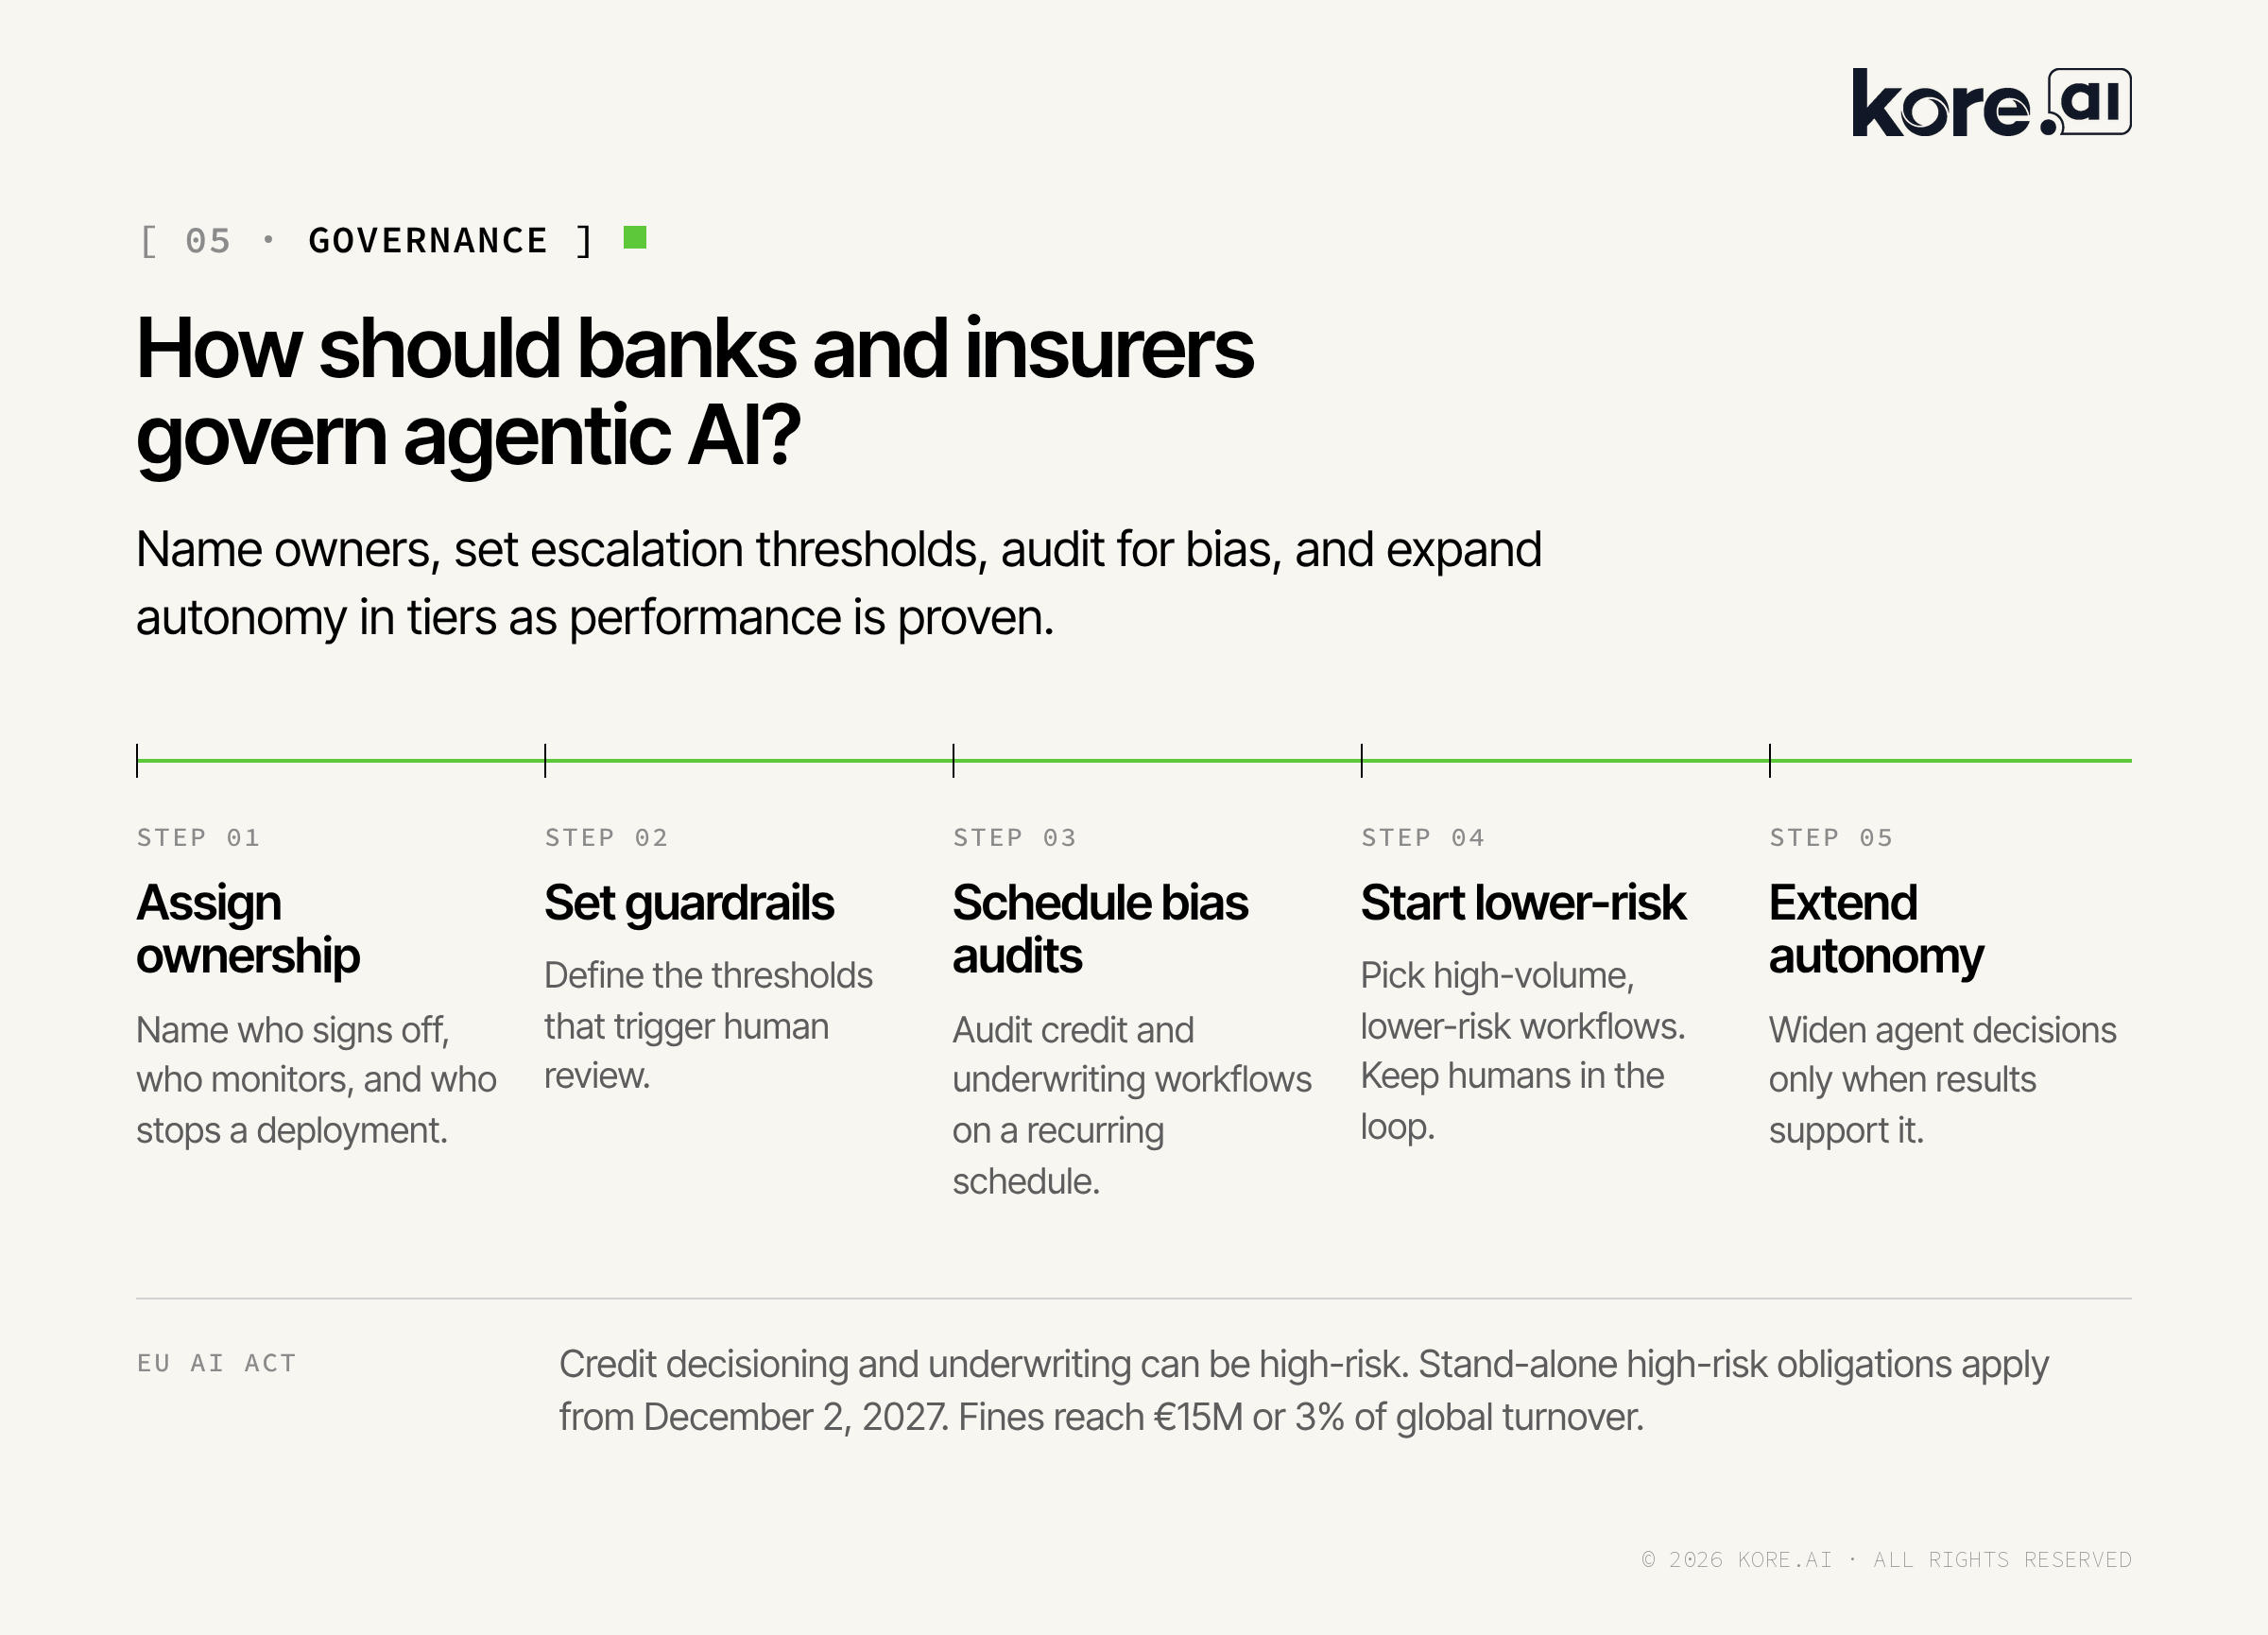
Banks and insurers should govern agentic AI with named ownership, defined escalation thresholds, recurring bias audits, and autonomy that expands in tiers as performance is proven. This approach gives compliance teams the oversight they need and gives business teams the pace they want.
- Assign ownership: Name who signs off on each AI deployment, who monitors performance, and who stops it if something goes wrong.
- Set guardrails: Define the thresholds that trigger human review, such as unusual decision patterns, a compliance flag, or a regulatory change.
- Schedule bias audits: For high-stakes workflows such as credit decisioning and underwriting, run bias audits on a recurring schedule.
- Start with lower-risk, high-volume workflows: Keep humans in the loop while the agents build a performance record.
- Extend autonomy as the data earns it: Widen the range of decisions agents complete on their own only when results support it.
How long does it take to deploy agentic AI in a bank or insurer?
Deployment time depends on scope. Banks and insurers that reach results fastest start with a few high-volume use cases and expand after early results. RCBC launched its assistant in July 2021 with 4 use cases, grew to more than 9 customer service functions, and reached ROI within its first year.
The phased path follows four steps:
- Pick one high-volume journey: The global investment manager automated address updates first, then added loan, balance, and withdrawal requests.
- Integrate the systems that journey needs: Typical integrations are core banking or policy administration, CRM, and secure authentication.
- Launch with human escalation: Pass full context to a human agent for every case the AI agent cannot resolve.
- Expand by use case: The global wealth management company rolled out in phases, from basic automation to compliance review and portfolio workflows.
Prebuilt agents shorten the start. The US national insurer launched AI agents with no prior conversational AI or self-service infrastructure.
How does Kore.ai support agentic AI in financial services and insurance?
Kore.ai provides prebuilt agentic applications for banking, insurance, and capital markets, such as AI for Banking, on Artemis, the Kore.ai Agent Platform. The applications are designed around FSI workflows and compliance requirements.
- Legacy systems: prebuilt integrations. Connectors for core and digital banking providers, including FIS, Fiserv, Jack Henry, Alkami, and Banno, let agents act across existing systems without waiting for modernization.
- Explainability: policy enforcement and audit trails. Human-in-the-loop controls, policy enforcement, and observability make every agent decision traceable for compliance teams and regulators.
- Security: certified controls. Kore.ai lists SOC 2, ISO 27001, PCI DSS, and GDPR compliance in its Trust Center.
- Fragmented journeys: multi-agent orchestration. Agents verify identity, execute across systems, and carry context across voice, web, chat, email, and mobile.
- Slow starts: prebuilt use cases. AI for Retail Banking covers customer experience (balances, money movement, card support and disputes, loan eligibility) and core banking operations (fraud and dispute management, payments, loan processing, onboarding, and account servicing).
- ROI measurement: evaluation and tuning. Agent Evals, Agent Insights, and Auto-Tuning measure agent performance and improve it after launch.
Learn more about Kore.ai AI for banking | Book a demo
What should FSI leaders do next?
FSI leaders should move one high-volume, lower-risk workflow from pilot to production with governance in place, measure it against metrics set before launch, and extend autonomy from there. Early movers are already compressing loan timelines from ten days to three.
FAQ
What is agentic AI in banking?
Agentic AI in banking is the use of AI agents that reason, decide, and execute multi-step banking workflows, such as loan processing, fraud investigation, KYC reviews, and card disputes, under rules that humans set. Unlike rule-based automation, agentic AI works across multiple systems, handles standard cases end to end, and escalates exceptions to people with the full case context attached.
How is agentic AI used in insurance?
Insurers use agentic AI for first notice of loss intake, claims triage, coverage validation, claims fraud detection, and underwriting. AI agents pull policy details, assess uploaded damage evidence, score fraud risk, and route each claim before an adjuster gets involved. Deloitte projects P&C insurers could save $80 billion to $160 billion by 2032 by using AI to reduce fraudulent claims.
Is agentic AI considered high-risk under the EU AI Act?
Many agentic AI uses in financial services can be classified as high-risk under the EU AI Act, including credit decisioning and some insurance underwriting. High-risk systems need documentation, human oversight, and fairness controls. Under the Digital Omnibus, stand-alone high-risk obligations apply from December 2, 2027, and breaches can bring fines of up to €15 million or 3% of global annual turnover.
What are the main barriers to scaling agentic AI in financial services?
The main barriers are fragmented data, legacy core systems without real-time APIs, explainability requirements, organizational resistance, security exposure, unclear ROI metrics, and missing governance. KPMG research finds 48% of organizations cite data governance concerns and 20% say their data is not ready. McKinsey finds no more than 10% of respondents scaling AI agents in any one business function.
How can a bank start with agentic AI?
A bank can start with a high-volume, lower-risk workflow, such as routine customer service requests or false positive triage in fraud alerts, and keep humans in the loop. Before launch, the bank can name an owner, set escalation thresholds, and define success metrics. Autonomy should expand only after the agents show reliable results against those metrics.
Share
Tags